Who authorises the expenditure, where is the money coming from, and who accounts to the Nigerian people?
There is an interesting constitutional anomaly developing around the Office of the First Lady of Nigeria. It is an institution that has acquired considerable political visibility, executive influence and apparent spending capacity without having a clearly defined constitutional or statutory foundation.
Mrs Oluremi Tinubu, the wife of President Bola Ahmed Tinubu, has increasingly occupied a public role involving charitable interventions, financial donations, social programmes and public ceremonies. Her activities have attracted considerable attention, not least because of the substantial sums of money being announced or distributed.
There is nothing inherently objectionable about a president’s wife engaging in charitable activities or supporting worthy causes. Indeed, public-spirited initiatives deserve encouragement. The difficulty begins when the distinction between private philanthropy and the expenditure of public money becomes blurred.
And in a constitutional democracy, that distinction is rather important.
An office created by convention, not by the Constitution
The Nigerian Constitution does not establish an Office of the First Lady. It does not prescribe the qualifications for the position, confer executive powers upon its occupant, establish a statutory budget or provide a constitutional mechanism for its supervision.
The office has evolved through political convention. Successive presidents’ wives have assumed public-facing roles, often associated with charitable causes, women’s welfare, maternal health, education and social intervention programmes.
However, political convention does not automatically become constitutional authority.
The President is elected under the Constitution. The First Lady is not elected on a joint presidential ticket, does not occupy an independently established executive office and does not derive executive authority from the Constitution merely by virtue of her marriage.
This distinction matters because the exercise of public power and the expenditure of public funds must have a lawful foundation.
A presidential spouse may enjoy political influence, access to government facilities and the opportunity to advocate for public causes. None of these circumstances, individually or collectively, creates an independent constitutional authority to appropriate or disburse public funds.
The PEP question and the ICPC
There is another interesting aspect to this institutional arrangement.
Mrs Tinubu is a politically exposed person (PEP) for anti-money-laundering and financial-compliance purposes by virtue of her close family relationship with the President, a person entrusted with a prominent public function.
The Money Laundering (Prevention and Prohibition) Act 2022 recognises PEPs and extends the relevant classification to family members and close associates of persons holding prominent public functions.
However, being a PEP does not mean being outside the jurisdiction of the Independent Corrupt Practices and Other Related Offences Commission (ICPC).
That would be a dangerous misunderstanding of the law.
The ICPC Act 2000 empowers the Commission to investigate allegations of corrupt practices. Its jurisdiction is not defeated simply because a person is not formally designated a public officer. Depending on the facts, individuals who offer, facilitate or participate in corrupt transactions may also attract liability.
The more interesting question is whether the First Lady’s office, its personnel and any public funds administered through it have been properly brought within the applicable public accountability and anti-corruption framework.
PEP status is a financial compliance classification, not a constitutional appointment and certainly not a licence to operate beyond public scrutiny.
Where is the money coming from?
This is the central question.
Mrs Tinubu has made a number of financial announcements and interventions. The public is entitled to know whether these are funded through personal resources, private donations, corporate contributions, government appropriations or some combination of these sources.
If the funds are personal, there should be no difficulty in saying so.
If they are private donations, the identity of the funding arrangements, the receiving institution and the applicable governance framework should be transparent.
But if public funds are involved, an entirely different set of constitutional and administrative obligations arises.
Sections 80 and 81 of the 1999 Constitution, as amended, establish the framework for the control and appropriation of public funds.
Section 80(2) provides that money cannot be withdrawn from the Consolidated Revenue Fund except where expenditure is authorised by the Constitution, an Appropriation Act, a Supplementary Appropriation Act or another relevant Act of the National Assembly.
Section 80(4) further requires withdrawals to be made in the manner prescribed by the National Assembly.
Section 81 provides the framework for the preparation of federal revenue and expenditure estimates and the appropriation of public funds.
Consequently, the question is not whether a presidential spouse has good intentions. The question is whether the expenditure has been authorised in accordance with the Constitution.
The presidential discretionary fund argument
One possible explanation is that the First Lady is accessing funds made available through the President’s discretionary expenditure arrangements.
But even that explanation requires scrutiny.
There is no general constitutional provision establishing an unlimited presidential discretionary fund from which the President can make payments to whomever he chooses without regard to appropriation and public financial administration.
Any discretionary expenditure must still be traceable to a lawful appropriation or other valid statutory authority.
The President’s constitutional position does not confer an unrestricted power to withdraw money from the national Treasury.
Nor can the First Lady independently exercise the President’s constitutional spending powers simply because she is his spouse.
If the President has authorised a particular public expenditure, the appropriate government institution must still identify the budgetary authority, process the expenditure and account for it.
The President’s signature, political approval or public announcement cannot substitute for the constitutional requirements governing public expenditure.
The ₦100 million Flamingos reward: A question of accountability
The latest announcement provides a particularly useful illustration.
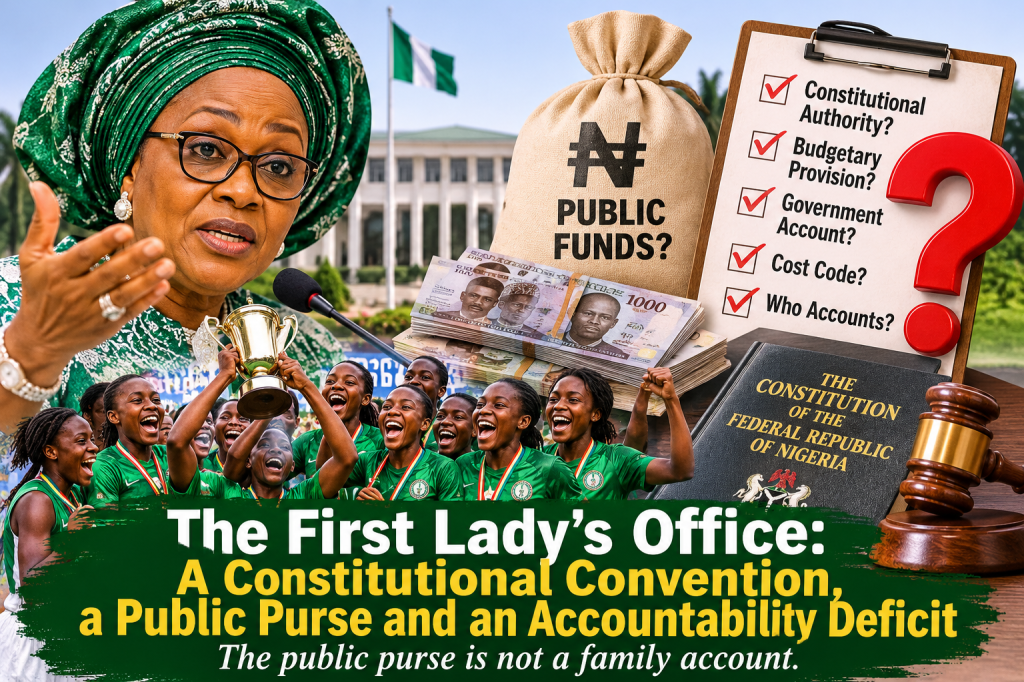
On 11 November 2026, Mrs Tinubu announced that the victorious Flamingos, Nigeria’s Under-17 women’s football team, would receive ₦100 million each following their historic FIFA U-17 Women’s World Cup triumph.
The announcement was made on behalf of the President.
The players are reportedly to receive Federal Government savings certificates, rather than immediate cash payments. The coach is to receive ₦100 million, while members of the technical crew are to receive ₦50 million each.
The precise total depends on the final number of eligible players and technical personnel. Nevertheless, the commitment runs into billions of naira.
It is a substantial public financial commitment, even if the certificates are not immediately redeemable.
The girls deserve recognition for their achievement. Their success is a source of national pride, and rewarding sporting excellence is a legitimate government objective.
But the constitutional question does not disappear because the beneficiaries are deserving.
Which appropriation provides for these rewards?
Is the expenditure coming from the Ministry of Finance, the Ministry of Sports, the Presidency or another government account?
What is the relevant budget code?
Which government institution authorised the commitment?
Who is responsible for processing and administering the savings certificates?
What is the source of the funds, and where will the expenditure appear in the government’s accounts?
These are ordinary questions of public financial administration. They should not be treated as hostile or disrespectful inquiries.
Where is the National Assembly?
The National Assembly has constitutional oversight responsibilities over the expenditure of public money.
Sections 88 and 89 of the Constitution empower the National Assembly and its committees to investigate the conduct of government departments and other persons or authorities responsible for administering or disbursing appropriated funds.
The purpose includes exposing corruption, inefficiency and waste in the administration of public expenditure.
The absence of a constitutionally established First Lady’s office raises a legitimate institutional question: under which ministry, department, agency or budgetary establishment are its publicly funded activities administered?
If an existing government department is responsible for the expenditure, its appropriation and the relevant National Assembly committee should provide the oversight framework.
If the First Lady’s office is independently receiving or administering public funds, the government should explain the legal and administrative basis for that arrangement.
There is no constitutional vacuum in which public money can be spent without accountability simply because the beneficiary or administrator occupies an unconventional political position.
The missing administrative paper trail
Anyone familiar with ordinary government financial administration understands that public expenditure is not supposed to operate on announcements and photographs.
There should be an identifiable administrative trail.
For every public payment, there should be an appropriate budgetary provision, authority to incur expenditure, payment documentation, relevant accounting codes, approvals and identifiable responsible officers.
There should also be a clear audit trail identifying the government account from which the money originated and the institution responsible for its administration.
Who is the accounting officer?
Who authorised the expenditure?
Who is the secondary approving officer?
What is the relevant cost centre?
Which account was debited?
Which accounting and audit records will capture the transaction?
These are not obscure technicalities. They are fundamental safeguards against the diversion, misuse and unaccountable expenditure of public money.
If the First Lady’s initiatives are financed through private contributions, the government should say so.
If they are financed through public funds, the government should identify the appropriation and the administrative arrangements.
And if the money comes from a combination of public and private sources, the two should be properly separated and accounted for.
The danger of government by informal authority
Nigeria has a long history of informal centres of power operating alongside constitutional institutions.
The problem is not necessarily the existence of informal influence. It is the danger that informal influence gradually acquires the practical powers of a public institution without assuming the corresponding legal obligations.
The First Lady may be an influential political figure. She may advocate for public policies, promote social causes and encourage private philanthropy.
But influence is not constitutional authority.
A public announcement is not an appropriation.
A presidential instruction is not a substitute for the public financial procedures required by law.
And a worthy beneficiary does not extinguish the public’s right to know where the money came from.
The Nigerian taxpayer should not have to guess whether a multimillion-naira donation is an act of private generosity or an expenditure of public funds.
Conclusion: The public purse is not a family account
The issue is not whether Mrs Tinubu should support Nigerian women, children, athletes or vulnerable citizens. Nobody should object to generosity directed towards worthwhile causes.
The issue is the constitutional and financial architecture supporting these activities.
The First Lady’s office is a product of political convention, not an independently created constitutional institution. If it is performing functions financed by the Nigerian Treasury, its expenditure must be traceable to lawful authority and subject to appropriate public accounting and oversight.
The government should therefore publish a clear account of the funding arrangements supporting the First Lady’s public initiatives.
It should identify the relevant budgetary provisions, the government accounts involved, the responsible accounting officers and the applicable audit and oversight arrangements.
There is an elementary constitutional principle at stake: public money must be accounted for, irrespective of the identity, political influence or family relationship of the person announcing its expenditure.
Nigeria cannot simultaneously insist that its citizens comply with elaborate tax obligations while allowing questions about billions of naira in public commitments to be dismissed as discourtesy towards the President’s family.
The Constitution does not recognise a family exemption from public accountability.
The First Lady may not have been elected, but the Nigerian taxpayer is certainly entitled to know who is paying for the activities conducted in her office.
The public purse is not a family account. And accountability is not an act of disrespect. It is an obligation of government.

